Luxury chess pieces symbolizing strategic wealth management

Financial Planning & Retirement Advice in Melbourne

Amber Wealth is a boutique financial planning practice based in Brighton, helping pre-retirees, retirees, and professionals across Bayside and greater Melbourne with retirement planning, superannuation, investments, personal insurance, and estate planning.

Book a Complimentary Wealth Consultation

or call us directly on 03 9964 0718 | after-hours appointments are available

Expertise

Strategic Financial Solutions

Our Retirement Journey

Retirement is more than reaching a certain age—it's about having the confidence and freedom to enjoy the lifestyle you've worked hard to achieve. We help you maximise your superannuation, create sustainable retirement income, reduce tax, and develop a personalised strategy that gives you financial security throughout every stage of retirement.

Explore Retirement Planning

Investment Management

Your investment portfolio should reflect your goals, risk tolerance and time horizon. We build and actively manage diversified portfolios designed to grow and protect your wealth while keeping your long-term objectives at the centre of every investment decision. Ongoing reviews ensure your strategy stays aligned as markets and your circumstances evolve.

Explore Investment Management

Protecting What Matters Most

Life is unpredictable, but the right protection can provide certainty when it matters most. We help you safeguard your family, income and lifestyle with tailored Life, Total & Permanent Disability (TPD), Trauma and Income Protection insurance, giving you confidence that you and your loved ones are financially protected if the unexpected happens.

Explore Personal Insurance

Beyond these core services, Amber Wealth also provides superannuation advice, Age Pension strategy, estate planning, mortgage broking, and property advocacy — each coordinated with your broader financial plan.

Serving Melbourne

Financial Planning Advice Across Melbourne

Amber Wealth is based in Brighton, in Melbourne's bayside, and we work with clients right across the metropolitan area — from the CBD and inner-eastern suburbs through Bayside and the south-east. Whether you're in Toorak, Malvern, Hawthorn, Camberwell, Richmond, South Melbourne, St Kilda, Caulfield, Doncaster, or closer to our Brighton office, the same considered, evidence-based advice applies.

As your Melbourne financial planner, we help individuals and families navigate the decisions that shape a secure retirement and a lasting financial position — from retirement planning and superannuation to investment strategies, retirement income, wealth protection, and broader financial planning.

Every plan is built around your actual numbers and circumstances, not a template. Appointments are available in person from our Brighton office, by phone, or by video — so clients across Melbourne and Australia can access tailored advice wherever they are. Get in touch to arrange a complimentary consultation, or learn more about Adam Sobczak and the practice.

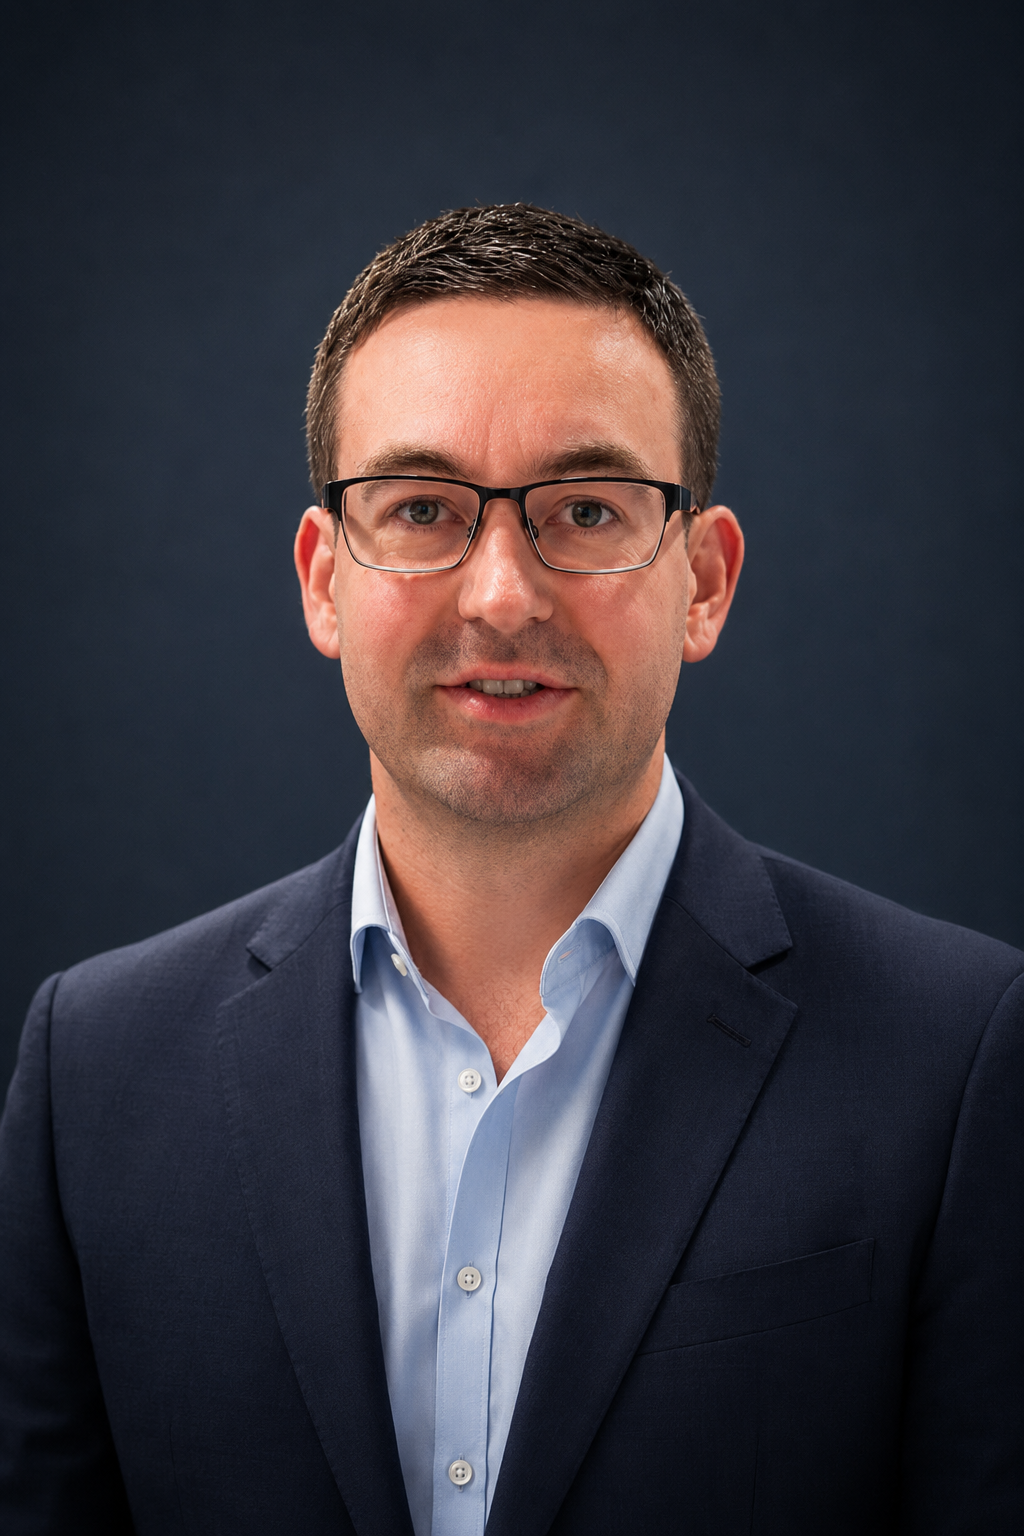
Adam Sobczak, Director and Principal Adviser

Adam Sobczak

Director and Principal Adviser

"True wealth management is not just about numbers; it's about the future security and legacy you build for your family."

Meet Adam – Helping Melbourne Retire with Confidence

With more than 15 years in financial services, advising clients since 2015, Adam has helped hundreds of families navigate complex financial landscapes.

Qualified Professional

Bachelor of Business majoring in Financial Risk Management and International Trade

Specialisation

From growing your wealth to planning your retirement and protecting what matters most, we provide tailored advice that gives you confidence at every stage of life.

Read Biography
Google Reviews

What Our Clients Say

Trusted by Melbourne families, retirees and professionals.

5.0
Based on 23 Google Reviews

Mark Harris

a month ago

Adam was so helpful with all the things that we needed to do with our Super and the money that we had in the bank left over from the side of the house
Victoria DUDAS

2 months ago

Adam from Amber Wealth, has made our transition into retirement so easy. He has done all the hard work for us and given us unlimited support and assistance. We should have started using Amber Wealth years before our retirement. The chosen investments made for us to continue financial security puts us at ease in the future. Geoff and I are extremely pleased with Amber Wealth and Adam is so easy to communicate with and is genuinely a pleasure to discuss all thing's financial.

M& M

4 months ago

Adam has been my financial advisor for over a decade, and his guidance has been invaluable. He’s helped me navigate complex situations and consistently provided clarity and solutions. I highly recommend him and his firm to anyone who wants steady, trustworthy advice.” Simple, honest, and it gets the point across!

karshini seneviratne

7 months ago

Adam from Amber Finance provided excellent financial advice, taking the time to understand both our current situation and future goals. His guidance was professional, clear, and extremely valuable. Thank you Adam!

PL Lee

7 months ago

Adam is an excellent financial planner who cares about his clients and will ensure the advice is in their best interest. He is very thorough and detailed, with extensive experience. I highly recommend his services.

Why Melbourne Trusts Amber Wealth & Adam

Our track record speaks for itself. We're committed to delivering exceptional results for our clients.

15+Years in Financial ServicesTrusted expertise in Australian financial markets
500+Families HelpedHelping Australians achieve financial independence
$100M+Funds Under ManagementManaging wealth with proven strategies, as at 1/7/2026
FASEAEXAM PASSED
FAAAMEMBER
100%PERSONALISED ADVICE

Retirement Planning Questions

There is no single dollar figure that applies to every Australian, because how much you need depends on your retirement age, lifestyle expectations, housing situation, other assets, and whether you will receive a full or part Age Pension. The Association of Superannuation Funds of Australia (ASFA) publishes a Retirement Standard that benchmarks these costs quarterly, suggesting roughly $690,000 for a couple and $595,000 for a single person for a comfortable retirement, assuming home ownership. These are benchmarks, not personal targets. Your actual figure could be higher or lower depending on whether you still have a mortgage, whether you plan to travel, and whether a part Age Pension supplements your income. A financial adviser can model your projected retirement income against your expected expenses to estimate the age at which you can comfortably stop working.

How much super you need to retire at 60 depends on the lifestyle you want, your housing situation, other savings, and how long your money needs to last. Retiring at 60 means your super may need to cover 25 to 30 years of living expenses, and you will not yet qualify for the Age Pension (currently age 67). ASFA's comfortable retirement benchmark suggests roughly $690,000 for a couple and $595,000 for a single person, but retiring earlier than 65 typically means needing more, because your money has less time to grow and must last longer. You can access your super from age 60 if you retire from the workforce, and withdrawals are generally tax-free from 60. A financial adviser can model whether your current balance and investment strategy will sustain your target lifestyle from 60 onwards.

How much super you need to retire at 65 depends on your lifestyle, housing costs, other assets, and whether you will receive an Age Pension. At 65, you can access your super regardless of whether you stop working, and withdrawals are tax-free. You will not yet qualify for the Age Pension (currently age 67), so your super may need to bridge a two-year gap before government support begins. ASFA's Retirement Standard suggests roughly $690,000 for a couple and $595,000 for a single person for a comfortable retirement, assuming home ownership. If you own your home outright and live modestly, you may need less. If you still have a mortgage or want to travel extensively, you may need more. A financial adviser can calculate a target specific to your circumstances and model whether you are on track.

Whether you can afford to retire early depends on your super balance, other savings, expected retirement expenses, and how long your money needs to last. In Australia, you can access your super from your preservation age (55 to 60 depending on your date of birth) if you retire from the workforce. From age 60, withdrawals are generally tax-free. Retiring early means your money has less time to grow and must last longer, and you will wait longer for the Age Pension (currently 67). Early retirement is achievable for some Australians with sufficient savings, but it requires careful planning to ensure your money does not run out. A financial adviser can assess whether early retirement is feasible for your circumstances and model the implications for your super, tax, and Age Pension.

How long your superannuation will last in retirement depends on your starting balance, how much you withdraw each year, your investment returns, inflation, fees, and whether you receive an Age Pension that supplements your income. If you withdraw too much, particularly in the early years, your balance may be depleted sooner than expected. A key risk is sequence-of-returns risk: a market downturn early in retirement, when you are drawing income, can reduce your balance faster than the same downturn would if it happened later. A financial adviser can model how long your super is projected to last under different withdrawal rates, return assumptions, and market scenarios, and help you choose a sustainable drawdown strategy for your circumstances.

How much you can safely spend each year in retirement depends on your total savings, investment returns, inflation, how long you live, and whether you receive an Age Pension. A commonly referenced guideline is the 4% to 5% rule, which suggests withdrawing around that percentage of your starting balance each year may be sustainable over a 30-year retirement. However, this is a general rule developed for US markets and does not account for Australian tax rules, Age Pension interactions, or your individual circumstances. In practice, a sustainable withdrawal rate depends on your asset allocation, the sequence of investment returns, and your life expectancy. Drawing too much early in retirement risks depleting your balance; drawing too little may mean living more frugally than necessary. A financial adviser can model a sustainable withdrawal rate for your actual savings and circumstances.

Whether you should pay off your mortgage before retirement depends on your interest rate, your superannuation and investment returns, your tax situation, and your preference for certainty. Paying off a mortgage before retirement provides certainty: it eliminates a regular expense and reduces the income you need to draw from super. However, if your mortgage interest rate is lower than the after-tax return you could earn by investing that money, it may be more efficient to invest rather than pay down the debt. This is a personal decision that depends on your risk tolerance as well as the numbers. Some retirees prefer the peace of mind of being debt-free even if the maths slightly favours investing. A financial adviser can model both scenarios for your actual numbers and help you weigh the financial and personal factors.

How you should structure your finances when you retire depends on your super balance, other assets, debt, Age Pension eligibility, tax position, and retirement goals. A typical retirement income structure involves transferring your super into an account-based pension (which provides tax-free income and tax-free investment earnings from age 60), supplementing with any Age Pension entitlement, and drawing on outside-super investments as needed. The order in which you draw on different sources matters for tax and Age Pension optimisation. You may also need to review your investment allocation, insurance cover, and estate plan. There is no single structure that is right for everyone; the right approach is built around your specific numbers and goals. A financial adviser can help you build a retirement income strategy that is tax-effective, sustainable, and aligned with your circumstances.
1 / 8

See all frequently asked questions →

Ready to Take Control of Your Financial Future?

Whether you're planning for retirement, growing your wealth, reviewing your super, or protecting your family, we're here to help. Book a complimentary consultation and discover how personalised financial advice can help you achieve your goals with confidence.